Budget 2026 changed the answer to a simple question. Who does not have to join Making Tax Digital for Income Tax? Four groups do not have to join until further notice. Budget 2026 announced the change, and secondary legislation is due before April 2027. It is not yet a settled rule in HMRC guidance, so check the current GOV.UK position before you act on it.
Three things are easy to confuse here. The first is a deferral until further notice. The second is a one-year deferral that ends in April 2027. The third is an exemption you must apply for. They have different effects, and they apply to different people.
The four groups deferred until further notice
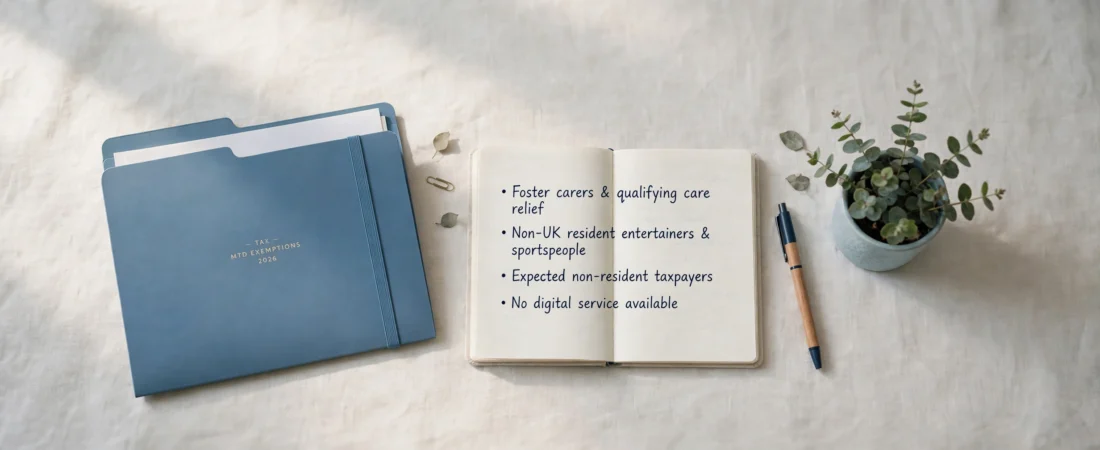
Budget 2026 announced that four groups do not have to join Making Tax Digital for Income Tax until further notice. The groups are:
- People eligible for qualifying care relief, such as foster carers and people who provide supported accommodation for adults.
- Non-UK resident foreign entertainers and sportspeople.
- Taxpayers who expect to become non-resident in the relevant tax year.
- Taxpayers for whom HMRC cannot provide a digital service for Making Tax Digital, including some insolvent customers who cannot currently sign up.
A temporary exemption already covered the first two groups for 2026 to 2027. It was due to expire in April 2027. Budget 2026 extends that cover indefinitely, in the sense that it sets no end date. The third group is new in form. It covers people who expect their residence status to change, not people who already filed a residence page. HMRC still has to confirm the detail for that group, including how it will handle the application. The fourth group covers a small number of customers for whom HMRC says the service does not currently work.
If you fall in one of these groups, you still need to meet your Income Tax obligations through existing arrangements. A deferral from Making Tax Digital is not a deferral from tax. It is not a removal of the annual Self Assessment return.
The groups that still join in April 2027
A one-year deferral is different from a deferral until further notice. Several groups held a temporary exemption for 2026 to 2027 only. They are due to join from April 2027 if their qualifying income is above the threshold for that year. Those groups include:
- People who received income from trusts or estates and completed the SA107 supplementary pages in their 2024 to 2025 return.
- People who made averaging claims in their 2024 to 2025 return, for example farmers and creative artists who used the SA103 pages.
- People who completed the SA109 residence pages in their 2024 to 2025 return, where that temporary cover does not also fall under the new expected non-resident deferral.
The April 2027 threshold is qualifying income over £30,000. Qualifying income is gross self-employment and property income, before expenses. Employment income, pensions and investment returns do not count toward it.
Budget 2026 also extended the penalty soft landing to people who join in April 2027. Under that announcement, people who join for the first time in April 2027 will not receive penalty points for late quarterly updates in 2027 to 2028. That is a change from the position in current GOV.UK guidance, which states the no-points position for 2026 to 2027 only. The soft landing does not cover a late annual tax return, and it does not remove the need to send every quarterly update before you can file that return. For the current GOV.UK wording, see MTD penalties guidance.
Automatic exemptions are not the same as applied exemptions
Some exemptions apply automatically, based on information HMRC holds. You do not need to contact HMRC for those. Examples in current guidance include qualifying income of £20,000 or less, and cases where a return is filed as a trustee or personal representative. Partnership income is also outside the current Making Tax Digital scope for Income Tax, and partnerships have no mandation date at present.
Other exemptions need an application. The main one is digital exclusion. Digital exclusion means it is not reasonably practicable for you to use compatible software to keep digital records or send updates and returns. GOV.UK gives examples such as age, a health condition or a disability that stops you using a computer, tablet or smartphone, a religious belief that is incompatible with using electronic communications or keeping electronic records, and a location where you cannot get internet access at home or at work and cannot get access at a suitable alternative location.
HMRC will not accept an application on its own if your only reasons are that Making Tax Digital will cost more, take more time, or that you are unfamiliar with accounting software. Filing on paper before, or having only a small number of records, is also not enough on its own.
How to apply for a digitally excluded exemption
You can apply for an MTD exemption yourself, or an authorised agent, friend or family member can apply on your behalf with your authorisation. You apply by phone or in writing, using the Self Assessment general enquiries contact details on GOV.UK. If you write, use the subject title shown on GOV.UK for a digitally excluded application.
You will need your National Insurance number, your name and address, and an explanation of why you think you should be exempt, with supporting information. For a digitally excluded application, you will also need to explain how you currently submit a tax return, why you are digitally excluded, whether you have an agent and what the agent will do, and any additional needs HMRC should know about.
HMRC aims to respond within 28 calendar days, although it may take longer if it needs more information. While you wait, keep your records as normal, and prepare to sign up and use Making Tax Digital if your application is not accepted. If you have already signed up and your circumstances have changed, apply for an exemption and continue to use Making Tax Digital while you wait.
If HMRC accepts your application, its letter will explain the type of exemption and how long it lasts. If it does not accept your application, the letter will explain why and how to appeal. You can appeal up to 30 days after the date on the letter.
What to check before you rely on a deferral
First, check which category fits your facts, not just your label. A foster carer with other self-employment income, a non-resident landlord, and a person who expects to move overseas can fall in different categories, even if their stories sound similar.
Second, check the date. A deferral until further notice has no set end date, but the legislation is still due. A one-year deferral ends in April 2027. A digitally excluded exemption may be permanent or may depend on your circumstances.
Third, keep filing. If you are exempt from Making Tax Digital, you must still report your income and gains in a Self Assessment tax return as normal. Exemption changes how you report, not whether you report.
Finally, do not assume your agent knows. If you receive a letter about sign-up, exemption or deferral, pass it to your agent straight away, and keep a copy for yourself.
Frequently asked questions
Does Budget 2026 exempt foster carers from Making Tax Digital for good?
Budget 2026 deferred Making Tax Digital for people eligible for qualifying care relief until further notice. Secondary legislation is due before April 2027, so treat the announcement as the current position, and check GOV.UK guidance once the legislation is published.
I completed SA109 in my 2024 to 2025 return. Am I covered until further notice?
Not automatically. The SA109 temporary cover was for 2026 to 2027 only. The new indefinite category covers taxpayers who expect to become non-resident, and its detail is still to be confirmed. Check which category fits your expected residence position.
Do I still file a tax return if I am exempt?
Yes. If you are exempt from Making Tax Digital, you still report your income and gains in a Self Assessment tax return as normal.
How long does a digital exclusion application take?
HMRC aims to respond within 28 calendar days of receiving your application. It may take longer if it needs more information. Keep your records as normal while you wait.
Will I get penalty points if I join in April 2027 and miss a quarterly update?
Budget 2026 announced no penalty points for late quarterly updates in 2027 to 2028 for people who join for the first time in April 2027. That announcement differs from current GOV.UK guidance for the 2026 to 2027 cohort, so check the updated guidance before you rely on it, and still send every update before you file your return.
Are partnerships in Making Tax Digital for Income Tax?
No, not at present. Partnership income is outside the current scope, and no mandation date has been set for partnerships. That position can change after consultation, so do not treat it as permanent.
Disclaimer
This guide provides general information about Making Tax Digital exemptions and deferrals as of November 2026. Tax rules and government announcements can change. Nothing in this article is tax advice. Always consult with a qualified tax professional about your specific circumstances. That’s what we’re here for. In accordance with our normal practice we give this reference in good faith and in confidence, without legal liability on the part of the author or the company. The author assumes no responsibility or liability for any errors or omissions in the content of this site
The information provided in this blog is for general guidance and educational purposes only and does not constitute financial, tax, accounting or legal advice. iFiler, registered in England under Company Registration Number 15996173, has prepared this content to offer general insights into financial and taxation matters. Although we make every effort to ensure the accuracy and relevance of the information at the time of publication, we give no guarantee regarding completeness, accuracy or suitability for your specific circumstances.
Readers should not act, or refrain from acting, based solely on the information contained in this content. Always get professional advice tailored to your personal or business situation before making any financial or tax-related decision. iFiler accepts no liability for any loss or damage arising from reliance on the information in this blog.